
Writer: Eric Bank


Editor: Lillian Guevara-Castro


Reviewer: Jon McDonald

Key Takeaways
I reviewed credit repair services for their dispute assistance, experience, and customer support. These top picks can help you challenge credit report errors.
-
Lexington Law: Best for professional help managing disputes across all three credit bureaus.
-
Sky Blue Credit Repair®: Best for personalized dispute support with a 90-day refund policy.
Think of your credit score as a key that can open doors or keep them closed. Correcting or removing inaccurate negative items from your credit reports may help improve your credit score and expand your borrowing options.
Below, we explain five ways to address negative items legally, from disputing errors yourself to hiring a credit repair service to help manage the process.
1. Hire a Credit Repair Company
If you’re looking for help correcting errors on your credit report, the following three credit repair services earn our top marks based on industry reputation, customer support, and our own reviews.
These services help you dispute inaccurate, incomplete, or outdated information with the credit bureaus that list it on your credit reports.
- Since 2004, Lexington Law Firm clients have seen over 84 million removals from their credit reports
- Get started today with a free online credit report assessment
- Cancel anytime
- See official site, terms, and details.

| Better Business Bureau | In Business Since | Monthly Cost | Reputation Score |
|---|---|---|---|
| See BBB Listing | 2004 | $139.95 | 8/10 |
- Best-in-class support
- In business since 1989
- Rapid 35-day dispute cycle, tailored to your situation
- 90-day 100% money-back guarantee
- Low $79 cost to get started, cancel or pause membership anytime
- See official site, terms, and details.
| Better Business Bureau | In Business Since | Monthly Cost | Reputation Score |
|---|---|---|---|
| A+ | 1989 | $79 | 9.5/10 |
- Free online assessment
- CreditRepair.com members saw over 8.8 million removals on their credit reports since 2012
- Free access to your credit report summary
- Three-step plan for checking, challenging and changing your credit report
- Online tools to help clients track results
- See official site, terms, and details.
| Better Business Bureau | In Business Since | Monthly Cost | Reputation Score |
|---|---|---|---|
| See BBB Listing | 2012 | $69.95+ | 8/10 |
The Fair Credit Reporting Act (FCRA) empowers you to challenge inaccuracies on your credit reports. You can do this either by mail or online through the websites of the three major credit reporting companies.
While you can try to fix your credit on your own, the process demands effort, patience, organization, and supporting documentation. For a fee, you can hire a credit repair organization to handle the work for you.
Credit repair organizations work with you by first identifying questionable and inaccurate items on your credit reports and then disputing those items with the credit bureaus.
Some disputes are straightforward, like the removal of outdated information. Other disputes need more effort, including providing evidence to challenge items and pushing the bureaus to verify questionable data. Correcting those errors may help your score, although the effect varies.
Most credit repair services offer a free consultation to review your credit reports and identify potential errors worth challenging. The credit specialist will review with you the different plans the company offers, what services come with each plan, and how much each plan will cost you.
If you decide to move forward, you can subscribe to a plan and pay a monthly fee to engage the service. Review the service agreement for billing terms and cancellation policies before enrolling.
The credit repair company will challenge reporting errors according to the services included in your chosen plan. In some cases, a straightforward dispute is enough to correct or remove an item.
In other cases, the service will submit the detailed objections and evidence required to address the problem.
Upon receipt of a credit report dispute submission, the Consumer Financial Protection Bureau says each credit reporting company has 30 days to investigate the matter and decide what to do.
In the course of the investigation, the bureau will forward disputes to the original credit provider that furnished the information. The information provider will review the credit report dispute and report back to the credit reporting bureau.
If the information provider discovers any inaccuracies, it must correct the information with the credit bureaus to which it reported the error. Once this process is completed, the credit reporting bureau will notify you in writing and provide a new copy of your report if any changes were made.
2. Dispute Inaccurate Items Yourself
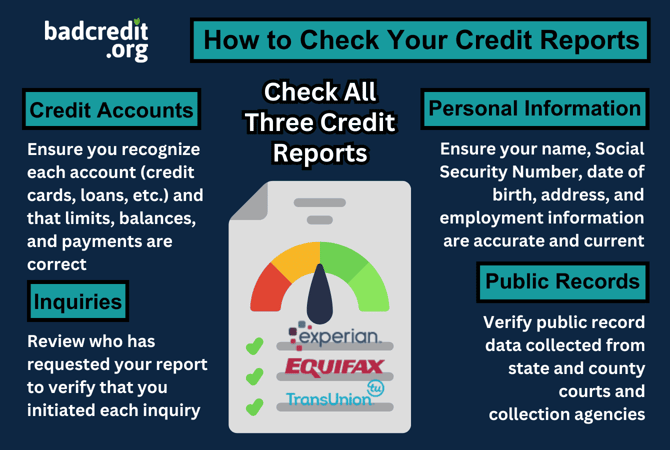
You can embark on DIY credit repair by ordering your three credit reports from AnnualCreditReport.com, a source of free credit reports authorized by the federal government. You need all three reports (one from each credit bureau, Experian, TransUnion, and Equifax) because creditors may report transactions to only one or two credit bureaus.
After receiving the reports, review the four sections for errors:
- Identification: Information identifying yourself, including your address, date of birth, and Social Security number. Incorrect information may be a tip-off that the report covers accounts that don’t belong to you.
- Tradelines: This contains your account data, which includes your use of credit and your borrowing activity. The data includes loan and credit account balances, payment history, and charge-offs. Collection accounts may appear in a separate section.
- Public records: Bankruptcy is the only public record currently included on standard credit reports from the three major bureaus. Civil judgments and tax liens no longer appear. Foreclosures and repossessions may still appear in account information.
- Inquiries: Hard inquiries are typically associated with applications for credit. These can lower your credit score. Soft inquiries have no impact on your score.
The hardest part of DIY credit repair is combing through your report data for accounts or account activity you don’t recognize, incorrectly reported negative credit file items (charge-offs, delinquencies, bankruptcies, etc.), and incorrect balances or payment statuses. You also should check for hard inquiries you didn’t authorize.
When you find incorrect information, submit a dispute through the credit bureau’s website, by phone, or mail. The bureau generally has 30 days to investigate, although some disputes can take up to 45 days.
Review the investigation results and any updated report to confirm that the error was corrected. Follow up with the bureau if its stated correction does not appear.
You have the right to follow up on an unresolved dispute and provide additional evidence. If you repeatedly submit the same dispute without new information, the credit reporting company might label the dispute as frivolous and disregard it.
3. Send a Pay-for-Delete Letter to Your Debt Collector
Your credit score may suffer when your credit report contains derogatory information (e.g., late payments, unpaid or paid collection events, charge-offs, debt settlements, etc.). You may be able to negotiate a collection account’s removal with a debt collector by using a pay-for-delete letter.
Collectors may refuse these requests, and credit bureau policies generally discourage deleting accurate information simply because a debt was paid.
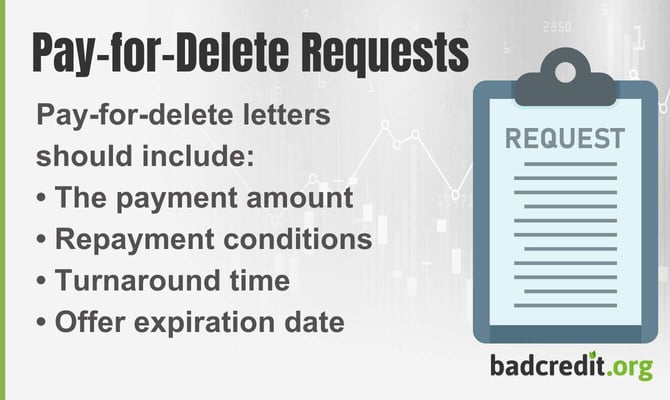
The idea behind a pay-for-delete letter is quite simple: you propose to pay off part or all of your debt, and in return, the collector agrees to request removal of its collection account from your credit report. This differs from a goodwill request, which asks for a courtesy adjustment without offering payment in exchange.
Even if the collector removes its account, the original creditor’s charge-off or late-payment history may remain.
The Fair Credit Reporting Act (FCRA) sets the rules for credit reporting as it applies to credit bureaus, companies that furnish credit information, and users of credit reports. You do not have a right to have accurate, current information deleted simply because you offer to pay a debt.
If an item is inaccurate or incomplete, dispute it directly for free. You do not need to pay a debt to exercise your right to challenge reporting errors.
Whenever you make a pay-for-delete agreement with a debt collector, it’s important to get it in writing. Before paying, make sure you understand the amount required, the account covered, and what the collector has agreed to do.
Payment alone does not require a collector to delete an accurately reported account.
4. Make a Goodwill Request For Deletion
If you have a good relationship with a creditor that has listed a late or missed payment, consider sending a goodwill request for deletion letter. The letter requests the original creditor to consider a courtesy adjustment to remove the offending item from your credit report. You can send the letter through the mail or make the request through email or on the phone.
Goodwill deletion requests work best when you have a long and positive relationship with the creditor. Bringing the account current before making the request can strengthen your case. The letter you send should be polite because the creditor is under no obligation to agree.
Just like other credit repair letters, you can find examples of goodwill request for deletion letters online for free. However, keep in mind that while a creditor might want to assist you, they could be limited by their policies or agreements with credit reporting agencies.
Nonetheless, you have nothing to lose by making the request, except for some of your time.
Since a goodwill letter is not considered an official credit dispute letter, you may never get a response back from the creditor — there are no mandatory deadlines for response. Your best bet is to demonstrate that the late payment was a rare oversight and explain the steps you’ve taken to prevent another missed payment.
Goodwill letters are usually less successful for more serious transgressions, such as collections and repos.
5. Wait for the Items to Age Off Your Reports
You should know two things regarding the effects of negative information on your credit score:
- Negative information generally has less influence on your score as it gets older.
- Items must be removed from your report after a set period. Once removed, they play no part in determining your credit score.
The following chart summarizes common reporting periods for items on your credit report:
| Item Type | Time on Credit Reports |
|---|---|
| Soft Credit Report Inquiry | No Report Impact |
| Hard Credit Report Inquiry | 2 Years |
| Delinquent Payment (30+ Days) | 7 Years |
| Vehicle Repossession | 7 Years |
| Defaulted Account | 7 Years |
| Foreclosure | 7 Years |
| Bankruptcy Discharge | 7-10 Years |
Among these items, a Chapter 7 bankruptcy hangs around for up to 10 years. Chapter 7 can discharge many debts, but certain obligations may remain, including child support, some taxes, and most student loans. A Chapter 13 bankruptcy is generally removed seven years after filing.
Credit reporting agencies are supposed to promptly remove any items that have aged off your credit report. If they miss this, you can file a dispute to remind them. The bureau must investigate and remove information that is too old to report.
Illegal Tactics to Avoid
Unfortunately, scam artists might try to sell you an illegal credit repair scheme. Falling for such a scam can lead to losing money and potentially facing civil or criminal charges.
One popular credit repair scam involves credit profile numbers (CPNs), which are nine-digit numbers formatted identically to Social Security numbers (SSNs). In fact, they are often SSNs that have been stolen or otherwise illegally obtained. Scammers may charge hundreds or thousands of dollars for a CPN.
Here’s the tactic: You are supposed to use a CPN instead of your regular SSN when filling out a credit application. You also may be told to give a phony name and address. This is a strictly illegal way to create a false identity with no connection to your existing credit history.
Using CPNs exposes you to charges of identity theft and misrepresenting your SSN, which is a federal crime. Even if you have bad credit, going to prison for using a CPN is definitely not worth it.
A variation on the CPN scam is to use Employer Identification Numbers (EINs), which are like SSNs for companies. While EINs are legal numbers when used properly, they are not substitutes for SSNs on credit applications. It is illegal to obtain an EIN under false pretenses.
Another scam involves hiring a dishonest credit counselor who adds fake information to your credit reports. This counselor invents false creditors and lenders, creating bogus transactions to make your report seem more appealing. This is also considered a crime.
Never be tempted to employ illegal practices to try and fool a creditor. You’ll likely be caught and have to suffer the consequences.
What Happens When an Item is Deleted From Your Credit Report?
Whenever your credit report is altered because of a dispute lodged by you or a credit repair service, the credit bureau must inform you in writing. You are then entitled to a fresh copy of your credit report from the bureau.
Many credit cards offer free alerts that inform you whenever your credit score changes. Thus, if an item deletion results in a change to your score, your credit card company may be the first to inform you of the good news. You also may get a free fraud alert service.
Here are the categories for the most popular credit-scoring model, FICO, so you can tell if you’ve leveled up:
| FICO Score Categories | Score Range |
|---|---|
| Exceptional | 800-850 |
| Very Good | 740-799 |
| Good | 670-739 |
| Fair | 580-669 |
| Poor | Below 580 |
When negative items are taken off your reports, your credit score is likely to improve. How much it improves depends on what type of item was removed and how old it was.
The credit bureau must send you written results about your dispute, which usually arrive within the initial 30-day window. If the results are favorable, you can instruct the bureau to notify anyone who received your report in the past six months.
How Long Does it Take to Remove Something From a Credit Report?
Credit bureaus generally have 30 days to investigate a dispute, although some investigations can take 45 days. Errors must be corrected or removed as part of resolving the dispute.
Since the same negative item can appear on the credit reports issued by three different bureaus, removal times may vary. If your original dispute fails, you have the right to resubmit it with additional evidence. This can add another month to the process.
How Many Points Will My Credit Score Go Up When a Derogatory Item is Removed?
The impact of an item deleted from your credit report depends on whether the item was negative, such as inquiries, late or missed payments, write-offs, collections, bankruptcies, settlements, liens, and foreclosures.
When these deletions happen, your credit score could jump by just a few points (like with inquiries) or even hundreds of points (as with bankruptcies). Removing a negative item is like lifting a weight off your score, letting it rise.
The impact on your score as a result of removing a negative item depends on the severity and the age of the item. Inquiries are not severe problems, so removing them will have, at best, a minimal impact on your score. Other items are more severe, so removing them could add dozens of points to your score.
The other factor is the item’s age. The impact of removal will always be greater if the item is relatively recent.
Even severely derogatory items begin to lose their bite after a couple of years. The impact of an item aging off your report will be muted because the negative effects have already eroded over time. Nonetheless, removing a negative item may improve your score, depending on the rest of your credit report.
Is it Better to Pay Off Collections or Wait?
Paying a collection may help your credit score even if the account remains on your report. The effect depends on the scoring model; FICO Score 9 and the FICO Score 10 suite disregard paid-in-full third-party collections.
As we’ve discussed, you might have some bargaining power when dealing with a debt collection agency. You can use this to your advantage by sending a pay-for-delete letter, offering to pay off the debt in exchange for removing the collection item from your credit report. You might offer the full amount, but don’t hesitate to ask for a partial reduction of the balance owed.
For example, suppose you had a $10,000 credit card balance and were unable to make payments. Eventually, the card issuer wrote off your account and sold it to a debt collection agency for 20 cents on the dollar. The issuer collected $2,000, which means the collection agency must collect at least that much just to break even.
Your original debt of $10,000 might not matter as much to the collector as it did to the credit card issuer. If the collector manages to collect $4,000, they make a 100% gross profit. So, the collector might be open to a pay-for-delete arrangement.
Once you settle the $4,000, the collector may, if agreed, take the item off your credit report, and your score may get a boost.
That is, a higher score will improve your access to credit and lower the amount of interest you’ll be charged. A higher credit limit will reduce your credit utilization ratio, which is part of the second-biggest factor in your credit — amounts owed:
| FICO Score Factor | Percentage of Your Score |
|---|---|
| Payment History | 35% |
| Amounts Owed | 30% |
| Credit History | 15% |
| Credit Mix | 10% |
| New Credit | 10% |
Paying off and removing a collection account from your credit report can lower your owed balance and enhance your payment history, thus improving your credit score. But if it’s not removed, settling the account might not impact your score at all.
Paying off the collection clearly demonstrates your resolve to re-establish your creditworthiness.
If you simply don’t care about your credit score, waiting to pay off the collection will allow you to keep the money you owe for a longer period. Even if you never repay the collector, the negative item will age off your credit report in seven years.
If you are already several years into the collection, you may choose to ignore the collector and let the item age away.
Of course, your collector may take a very different view of the situation and haul you into court to grab the money you owe. A lawsuit can have serious financial consequences, even though civil judgments no longer appear on standard credit reports from the three major bureaus.
If a collection is accurately reported on your credit report, a dispute (whether initiated by you or a credit repair service) won’t remove it. The only way to get rid of a bona fide collection is to successfully negotiate a pay-for-delete agreement or for the item to age off after seven years.
How Do I Remove Negative Items From My Credit Report For Free?
You can remove negative items for free, but you’ll have to invest some sweat equity in the form of time and attention. If you’re watching every penny, it’s good to know you can get your credit reports and submit disputes for free.
You start your cost-free DIY odyssey by ordering a free credit report from AnnualCreditReport.com. This source is authorized by the federal government to give you a free credit report as often as once per week from each consumer reporting company: Equifax, TransUnion, and Experian.
If, after thoroughly checking your reports, you spot items you want to dispute, you can do so for free online, which saves you the cost of paper, ink, and postage.
Tackling this alone means you’ll handle all the record-keeping and tracking of disputes that a credit repair service would normally manage. While this will take up your time, it won’t cost you any money.
Perhaps you would like to make the job easier by spending just a little money. If so, consider a software package as an alternative to support from a credit repair service. For example, Credit Versio offers software-as-a-service for less than $20 per month that supports consumers who wish to dispute items on their credit reports.
The Credit Versio package has provisions for importing your credit reports and helping you identify items for potential dispute. The software can help you generate professional-looking dispute letters and provides $1 million in identity theft insurance. If you become a victim of identity theft, you’ll want to request a credit freeze.
Credit repair services can range from about $80 to $150 a month. These companies aim to have you subscribe for at least six months, so costs may run anywhere from $480 to $900 for the period. That’s how much money you’ll save if you do it yourself.
Can Disputes Hurt Your Credit?
There is no reason for a dispute to ever hurt your credit. At worst, it may have no impact on your credit score.
However, your score should rise if a dispute successfully results in the removal of derogatory items from your credit report.
Perhaps the only negative outcome of a credit dispute occurs when consumers abuse the process by submitting frivolous challenges. Eventually, a credit agency will recognize this kind of abuse and just ignore your dispute submissions.
Like the boy who cried wolf, this can come back to bite you when you suffer from a real credit report error.
Do Credit Bureaus Really Investigate Disputes?
The credit bureaus hand off investigations to the original creditor that furnished the disputed information.
If you dispute a late payment on your credit card, the credit reporting agency will forward your dispute to the card issuer for investigation. They need to wrap up this process within 30 days after you submit the dispute.
There could be situations where a credit reporting agency steps in to investigate a dispute directly. This might happen, for example, if data was properly sent by a creditor but got corrupted within the credit agency’s systems.
You Have Options to Legally Remove Items from Your Credit Report
It won’t cost you anything to have a free consultation with one of our top-rated credit repair services. This process can, at the least, tell you where your reports stand and whether its services can help you legally remove items from your credit reports.
Knowing which items you can legally dispute will give you an idea of whether you can go it alone or you’d feel more comfortable enlisting a service. Check out Sky Blue Credit Repair’s money-back guarantee if you’re wary of spending money on a credit repair company.


