
Writer: Eric Bank


Editor: Lillian Guevara-Castro


Reviewer: Ashley Fricker

Key Takeaways
We did some digging to find credit cards that welcome applicants with bad credit, offer a straightforward application process, and don’t require a security deposit:
-
Fortiva® Cash Back Rewards Mastercard: Best for earning cash back on everyday expenses without a security deposit.
-
Reflex® Platinum Mastercard®: Best if you have bad credit and want to prequalify before applying.
Looking for guaranteed approval credit cards with no deposit? The unsecured options below give people with credit challenges a path to applying without a security deposit, with approval based on the issuer’s requirements.
We’ve also included store cards that may be easier to quality for. If your credit needs a fresh start, these options could help you build a stronger history when you pay on time and keep your balances low.
Easy-to-Get Unsecured Credit Cards
The yin of these cards is that you can get them without having good credit or a security deposit. The yang is their high cost and meager benefits. Perhaps not a life-altering dilemma, but one that deserves some careful attention.
Open-loop means these cards can be used anywhere the payment network — i.e., Visa or Mastercard — is accepted. We consider the following to be the best unsecured credit cards for poor credit:
- Earn Cash Back Rewards* – 3% on Eligible Gas, Groceries, and Utilities, and 1% on All Other Eligible Purchases
- Use Anywhere Mastercard is Accepted
- No Security Deposit
- $0 fraud liability**
- Free access to your Credit Score†
*See Program Terms for important information about the cash back rewards program.
**Fraud liability subject to Mastercard rules.
† Your credit score will be available in your online account starting 60 days after your account is opened. (Registration required.) The free VantageScore 4.0 credit score provided by TransUnion® is for educational purposes only. This score may not be used by The Bank of Missouri (the issuer of this card) or other creditors to make credit decisions.

| Application Length | Interest Rate | Reports Monthly | Reputation Score |
|---|---|---|---|
| 7 minutes | 36% Fixed | Yes | 8.0/10 |
The Fortiva® Cash Back Rewards Mastercard lets you prequalify for a credit limit of up to $1,000 based on your creditworthiness and income. It’s yet another card that offers cash back rewards on select purchases.
You can gradually build your credit with consistent, on-time payments, and you don’t need good credit to apply. Just be mindful of the high APR and annual fee.
- Up to $1,000 Initial Credit Limit
- See if you Pre-Qualify with No Impact to your Credit Score
- Less than perfect credit? We understand. The Reflex Mastercard is ideal for people looking to rebuild their credit.
- Unsecured credit card requires No Security Deposit
- Perfect card for everyday purchases and unexpected expenses
- Monthly reporting to the three major credit bureaus
- Use your card everywhere Mastercard is accepted at millions of locations
- Enjoy peace of mind with Mastercard Zero Liability Protection for unauthorized purchases (subject to Mastercard guidelines)
- Apply with Confidence! There is no impact to your credit score if you’re not approved. See terms.
| Application Length | Interest Rate | Reports Monthly | Reputation Score |
|---|---|---|---|
| 8 minutes | 35.90% Fixed | Yes | 8.0/10 |
The Reflex® Platinum Mastercard® is an unsecured card that is ideal for those looking to build credit. The issuer works with people of all credit stripes.
The Reflex® Platinum Mastercard® might start with a modest credit limit, but by making timely payments and using the card wisely, you can expect to see an increase in your credit health as Reflex reports monthly to all three major credit bureaus.
- See if you’re pre-approved with no impact to your credit score.
- Qualify for rewards like a credit limit increase (subject to credit approval) or APR decrease in as little as six months.
- Earn unlimited 1% cash back on purchases.
- Building your credit? We report to the major credit bureaus and good payment habits can pay off.
- Easily manage your account and make payments using BrightWay App.
- BrightWay cards are issued by WebBank.
- See the OneMain BrightWay® Card rates and fees.*
| Application Length | Interest Rate | Reports Monthly | Reputation Score |
|---|---|---|---|
| 5 minutes | 35.99%* | Yes | 9.5/10 |
The OneMain BrightWay® Card allows cardholders to earn cash back on purchases while building credit history through monthly reporting to the credit bureaus. You can fill out a quick application to see if you’re pre-approved without any impact on your credit score.
Once you receive the card and start using it, you might qualify for a higher credit limit or a lower APR after just six months, provided you make timely payments.
- Earn Cash Back Rewards* – 3% on Eligible Gas, Groceries, and Utilities, and 1% on All Other Eligible Purchases
- Up to $1,000 credit limit subject to credit approval
- Prequalify** without affecting your credit score
- No security deposit
- Free Access to your Credit Score†
- Review Cardholder Agreement for rate and fee information
*See Program Terms for important information about the cash back rewards program.
** Prequalify means that you authorize us to make a soft inquiry into your credit history (that will not affect your credit) to create an offer. If you accept an offer a hard inquiry will be made. Final approval is not guaranteed if you do not meet all applicable criteria (including adequate proof of ability to repay). Income verification through access to your bank account information may be required.
† Your credit score will be available in your online account starting 60 days after your account is opened. (Registration required.) The free VantageScore 4.0 credit score provided by TransUnion® is for educational purposes only. This score may not be used by The Bank of Missouri (the issuer of this card) or other creditors to make credit decisions.
| Application Length | Interest Rate | Reports Monthly | Reputation Score |
|---|---|---|---|
| 7 minutes | 36% Fixed | Yes | 8.0/10 |
The Aspire® Cash Back Rewards Mastercard welcomes applications from consumers with fair or poor credit. The Bank of Missouri offers this cash rewards credit card, which may give you a relatively high credit limit and lucrative cash back rewards.
This card also gives you access to free credit scores from Equifax, making it easier for you to keep track of your credit. By paying your entire balance each billing cycle, you can dodge its high APR.
Easy-Approval Store Cards For Bad Credit
Store credit cards can be easier to obtain than other types of credit cards. This is because you can use them only with the issuing store — the meaning of closed-loop — and they usually have modest spending limits.
Store card issuers often assume less default risk because they don’t give cardholders access to large credit lines, at least in the beginning.
5. Target Circle™ Card
The Target Circle™ Card gives you 5% off all eligible purchases made in-store or online. You can stack this discount with manufacturing and store coupons.

The card doesn’t charge an annual fee. It excludes certain purchases from the 5% discount, including prescriptions, over-the-counter pharmacy items, gift cards, select restaurant merchants, and Target Optical™ eye exams.
You can also earn a $50 Target Circle Rewards credit on a future purchase after you make $50 in eligible purchases in the first 60 days.
6. Amazon Store Card
The Amazon Store Card favors cardholders who are also Prime members, as they’ll get 5% back on Amazon.com purchases.
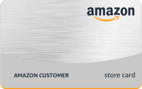
Although the card has no annual fee, Prime charges apply. Amazon may offer special deferred interest financing on purchases above a set price.
But if you don’t repay the balance by the end of the 0% interest period, you’ll be charged deferred interest for the entire purchase amount, reversing any savings you thought you had.
Personal Loans That Offer Fast Approval Decisions
If you’re applying for a credit card because you need cash fast, you might be better served by applying for a personal loan. Subprime credit cards can come with low limits and lots of fees, restricting the amount of credit you can access.
With a personal loan, you may be able to access the funds you need at a comparable APR and make predictable monthly payments until it’s settled.
These networks can connect you with lenders quickly, and you won’t have to worry about a hard credit check when you fill out their prequalification forms.
- Personal loans from $500 to $35,000
- All credit types are considered and welcome
- Simple, no credit impact form
- Helping consumers since 2001
- 4.7 out of 5 Trustpilot rating with 2,000+ reviews!
- See official site, terms, and details.
| Loan Amount | Interest Rate | Loan Term | Loan Example |
|---|---|---|---|
| $500 to $35,000 | 5.99% – 35.99% | 60 Days to 72 Months | See representative example |
24/7 Lending Group works with a network of lenders that understand if you’ve had credit issues. In fact, many of them specialize in funding people who have bad credit.
After you fill out the online form, you’ll get a matching decision quickly, and can connect with a lender that is willing to work with you. The service is free, and there’s no obligation to accept any offer you receive.
The process also results in just a soft credit inquiry, so your credit won’t be impacted.
8. MoneyMutual
- Short-term loans up to $5,000
- Online marketplace of lenders
- Funds available in as few as 24 hours
- Simple online form takes less than 5 minutes
- Trusted by more than 2 million customers
- See official site, terms, and details.
| Loan Amount | Interest Rate | Loan Term | Loan Example |
|---|---|---|---|
| Up to $5,000 | Varies | Varies | See representative example |
With MoneyMutual, you can find a short-term loan up to $5,000 through a vast network of lenders. The process is fast, and if you are approved through one of the lenders you match with, you could receive the funds in your account in as little as 24 hours.
Interest rates can vary widely, so you’ll want to make sure your monthly payments fit your budget. But you could qualify for a larger loan than a subprime credit card would offer as an initial credit limit (especially if it immediately charges an annual fee).
9. Avant
- Personal loans of $2,000 to $35,000
- Compare rates in 3 minutes without affecting your credit
- 550 minimum credit score required
- One form taps into 22 lenders at once
- Powered by Credible
- See official site, terms, and details.
| Loan Amount | Interest Rate | Loan Term | Loan Example |
|---|---|---|---|
| $1,000 to $35,000 | 9.99% – 35.99% | 24 to 60 Months | See representative example |
Avant only requires a minimum credit score of 550 to match with a lender in its network, so bad credit doesn’t need to keep you from applying. Its loan options range from $1,000 to $35,000, but borrowers who have had credit issues will likely only be approved for funding on the low end of that.
The prequalification form is short, and Avant‘s matching services are free. So, if you need cash fast for an emergency, it is an accessible way to check your options.
Do Credit Cards Offer Guaranteed Approval?
No credit card approves 100% of applicants, although some have high acceptance rates. Card issuers won’t approve cards for consumers under 18 or for those who can’t satisfactorily verify their identity.
If an issuer denies your credit card application, you should receive an Adverse Action Notice explaining why. You can use the information to address your credit deficiencies before reapplying.

In some cases, the issuer may base the rejection on incorrect information in your credit reports. If so, you should fix your reports, either on your own or with a credit repair company. You can apply for a credit card again once you correct each credit report.
Many credit cards offer a prequalification step that lets you know if you’re eligible to apply. This step doesn’t affect your credit score and doesn’t guarantee final approval. However, unless unexpected issues arise, your chances of approval should be quite good.
What Is the Easiest Card to Get Approved For?
Secured, student, and store cards are among the easiest to get. In fact, some secured card issuers even skip credit checks. These could be just what you need if your credit score is quite low.
If a secured credit card isn’t an option, consider a prepaid debit card as a fantastic alternative. It doesn’t require a credit history or a bank account.
Here are more details on easy-to-get cards:
Secured Credit Cards
Secured credit cards can help consumers who card issuers perceive as “risky” due to their having no, limited, or bad credit. These cards require you to post cash collateral (usually) equal to your credit line. They are excellent tools for establishing or rebuilding credit when you consistently pay your bills on time.
The minimum credit line for a secured credit card is typically around $200. Some cards offer higher credit limits in exchange for larger security deposits.
There are also partially secured credit cards, in which your deposit is less than your assigned credit limit. Receiving a partially secured line of credit is based on your credit history and is at the issuer’s sole discretion.
If you’re curious about how a secured credit card can help you improve your financial situation, check out our handy tool that lets you customize a strategy:
After you send your deposit to the issuer, they’ll mail your credit card, which functions just like an unsecured one. Secured cards appear identical to their unsecured counterparts. So, whether you’re booking a hotel online or buying groceries, the merchant won’t know it’s a secured card.
Most secured cards may raise your credit limit or refund your security deposit after a set period of responsible use, often about six months. If you use the card well and strengthen your credit profile, you could move up to a better unsecured card.
Student Credit Cards
Although not strictly for people with poor credit, student credit cards have more flexible credit score requirements, and most don’t require you to have any credit history.
These cards are relatively easy to obtain if you attend college or trade school at least half-time. Most offer low fees and quality perks, such as purchase rewards and credits for good grades.
Store Cards
As previously discussed, getting a store card is usually straightforward, as most are closed-loop, meaning you can use them only at the issuing store and its affiliates.
Department store cashiers often push the store’s credit cards at checkout, offering same-day discounts and other goodies. Some merchants offer open-loop credit cards.
These function as unsecured credit cards that can be used anywhere, but are harder to get approved for.
Credit Union Credit Cards
Credit unions are generally more welcoming than banks because they’re member-run organizations that serve their own community. They often provide a variety of credit cards with different requirements, catering to all consumers.
While credit union cards usually have lower APRs and costs, their rewards programs may not be as attractive as those from bigger banks.
Prepaid Debit Cards
Prepaid debit cards don’t offer credit, which makes them incredibly easy to acquire. You don’t need a credit history or a bank account to get one. They work like debit cards linked to checking accounts, but they draw from the funds you load onto them.
You can use these cards to make purchases, pay bills, withdraw cash from ATMs, and transfer money to others. Most prepaid cards impose monthly or pay-as-you-go fees, plus additional fees for certain transactions.
Since they don’t provide credit, you can’t use prepaid debit cards to build credit.
What Guarantees Can Credit Card Applicants Get?
While credit card issuers can’t offer guarantees for final approval, they do provide the following:
- Prequalification: Issuers guarantee a swift decision on whether you prequalify for their cards without impacting your credit score. As previously mentioned, successful preapproval is neither necessary nor sufficient to guarantee final acceptance. But it certainly can help avoid needlessly affecting your credit score when you don’t have any chance of final approval.
- Instant final decisions: Most issuers guarantee a swift final decision when you formally apply for a credit card, even if you don’t first undergo prequalification. They can do so because they perform an instant, hard credit inquiry to check your suitability. Usually, the only reasons for delay are conflicting data or an inability to verify your identity. You may have to provide additional information and documents to win final approval.
- No Hard Credit Check for Some Cards: More than one secured credit card, including the opensky® Secured Visa® Credit Card, guarantees no credit check when you apply. In other words, limited, no, or poor credit won’t prevent you from getting these cards. Other secured cards may perform credit checks without giving much weight to the results. Generally, secured cards show much more interest in your cash deposit than in your credit score.
You can improve your approval odds for certain cards by recruiting a cosigner, although many card issuers don’t accept them. A cosigner is equally responsible for timely payments, reducing the issuer’s risk that primary cardholders will default on their debt.
Alternatively, you may consider asking a friend or relative to make you an authorized user of their credit card. You’ll receive your own card copy with spending privileges, although the owner may restrict your credit limit. Almost all credit cards accept authorized users.
What Credit Score Do I Need For Approval?
For some secured or student credit cards, you may not need a credit score at all. Unsecured cards do check credit, but we’ve heard of scores as low as 450 winning approval from issuers of store credit cards.
Before you apply for a credit card, it’s a good idea to check your credit scores to determine which card might be the best fit for you. Remember, you have multiple credit scores, and they can vary because of differences in your credit reports and the scoring systems used.
For example, here are the scoring ranges for VantageScore and FICO, the most popular scoring models:
| FICO Score Categories | Score Range | VantageScore Categories | Score Range |
|---|---|---|---|
| Exceptional | 800-850 | Superprime | 781-850 |
| Very Good | 740-799 | Prime | 661-780 |
| Good | 670-739 | Near prime | 601-660 |
| Fair | 580-669 | Subprime | 501-600 |
| Poor | Below 580 | Deep Subprime | 300-500 |
You can purchase your FICO scores directly from myFICO.com, but several other sources offer free credit scores (although not all of them are FICO scores).
You can also get free copies of each credit report from AnnualCreditReport.com as often as once per week. Getting a copy of your credit reports allows you to review the factors that determine your credit score.
If you find mistakes, you can dispute them independently, but hiring a credit repair company may be more effective.
What Interest Rate and Credit Limit Should I Expect?
If you have bad credit, you may see APRs starting at 24.9% and opening credit limits as low as $200. The good news is that terms often get better as your credit score improves.
You can guarantee a 0% interest rate by paying your balance in full by the monthly due date. But beware of the few credit cards that provide no grace periods — they charge interest starting on the transaction date.
This chart shares how the average credit card interest rate varies among credit tiers:
| Category | Average APR |
|---|---|
| Secured Cards | 21.81% |
| Store Cards | 33.14% |
| Bad Credit | 30.51% |
| Fair Credit | 26.95% |
| Good Credit | 23.31% |
| Excellent Credit | 17.11% |
Secured and student credit cards for people with bad or no credit typically offer better APRs than subprime unsecured cards. They are also far less expensive because they don’t overwhelm you with the nuisance fees that come with unsecured subprime cards.
We’ve seen some unsecured cards with a steep APR of 36% and fees over $150 a year. Generally, you’ll do better with a secured credit card. Keep in mind, deposits are refundable, but fees aren’t.
How Do I Use an Unsecured Credit Card to Build Credit?
Getting a credit card is a solid first step toward building your credit history. But if you want to see real progress, you’ll need to pay on time and keep the account in good shape. Here’s what that means:
- Paying your bills on time: 35% of your FICO score comes from your payment history. Consistently paying your bills on time will help your credit score, but payments more than 30 days late can hurt it. The damage will worsen if you default on your account, undergo collection, or enter bankruptcy.
- Paying down debt: Another 30% of your FICO score focuses on your debt levels. One important metric is the credit utilization ratio, which is the amount of credit card balances outstanding versus your credit card spending limits. The general rule is to keep this ratio under 30%.
- Refraining from too many applications: Occasionally applying for a new credit card shouldn’t impact your score very much, but submitting many applications within a short period can do damage, as FICO may assume you are experiencing financial distress. It’s safest to wait six months between new credit card applications.
- Keeping old credit card accounts open: The age of your accounts influences your credit score. FICO rewards you for maintaining credit accounts over a long period. Keeping old credit cards open and occasionally using them will help your credit score by lengthening your average account age.
If you’ve begun building your credit with a loan but haven’t added a credit card yet, getting one can enhance both your credit mix and score. Plus, a store credit card might give your score an extra boost. However, the benefits of a varied credit mix are limited, so only open new accounts if you really need them.
You Don’t Need a Deposit to Get a Credit Card
We’ve debunked the myth of guaranteed approval credit cards with no deposit, but highlighted several cards that are super easy to get. Even if you have poor credit, there’s a strong chance an issuer of unsecured credit cards is ready to assist you.
Although applying for a credit card usually has only a small effect on a low score, it’s still smart to focus on realistic options. Many unsecured cards offer prequalification and a quick decision.
Starting there can save you time and help you narrow down the cards you’re most likely to qualify for.